Most homeowners know they have insurance. They pay the premium, keep the policy documents, and assume that if something serious happens to their home, their insurer will help cover the damage. But there is one important question many people never ask until they are standing in front of a damaged house: “How much would it actually cost to rebuild my home today?”
The answer may be very different from the number you paid when you originally bought the property. Construction costs, labor, building materials and local conditions can change over time. That means a homeowners insurance policy that once seemed adequate may not necessarily provide the same level of protection years later.
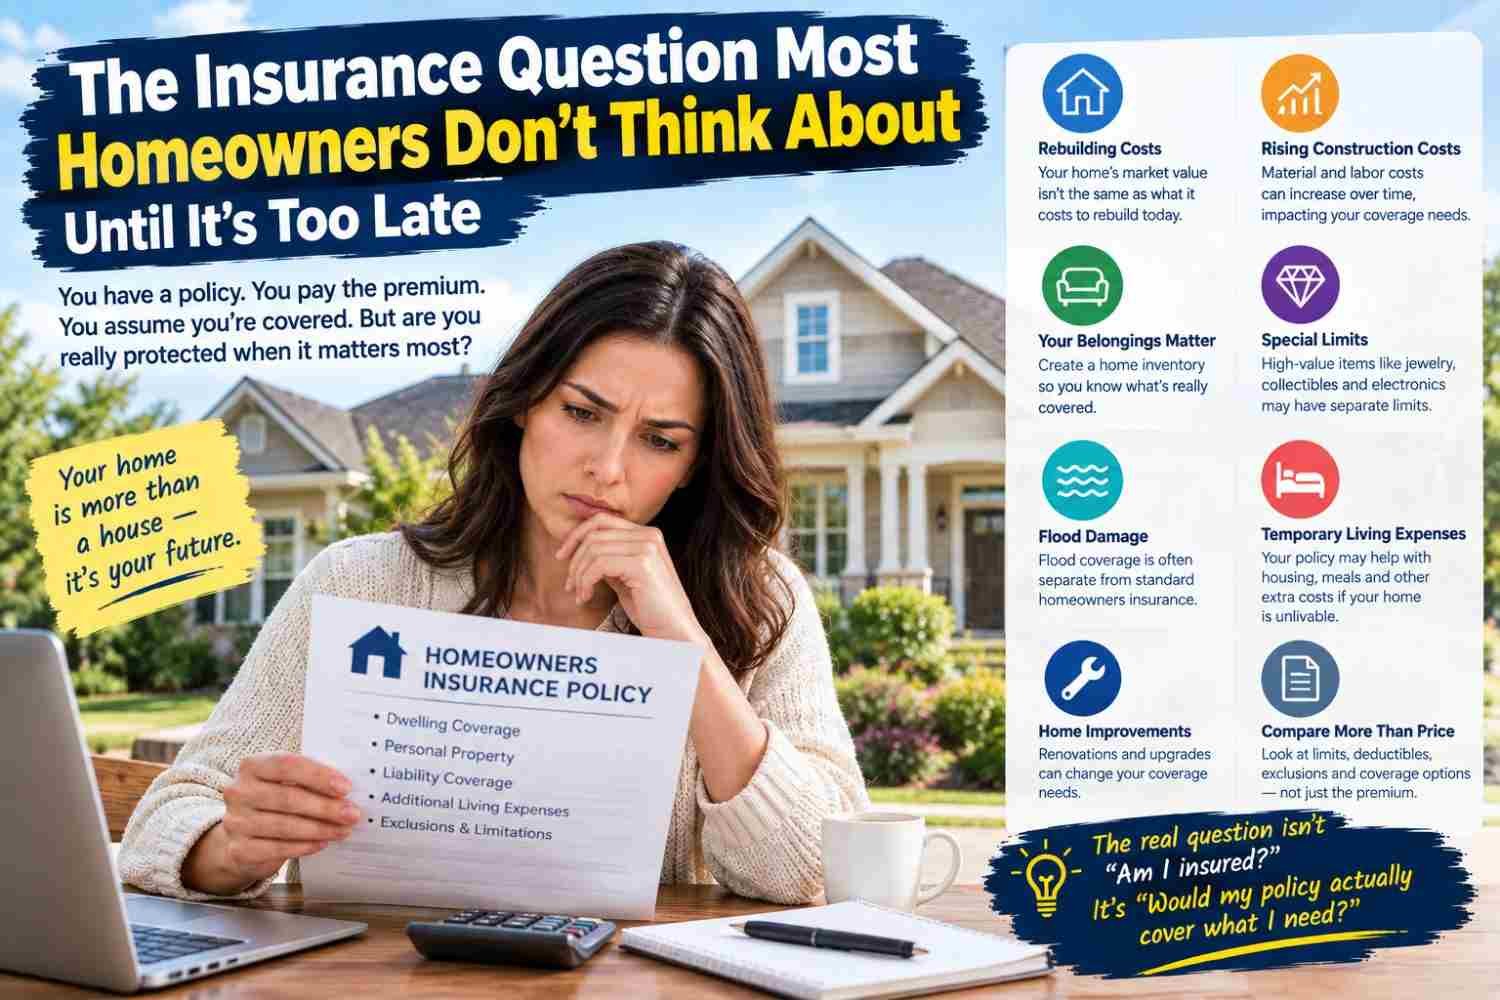
Your Home’s Market Value Isn’t the Same as Its Rebuilding Cost
One of the most confusing parts of homeowners insurance is the difference between what a home is worth on the real estate market and what it would cost to rebuild the structure. A home’s market value can be heavily influenced by the land, neighborhood, location and local housing demand. Rebuilding costs are driven by construction materials, labor and the work required to replace the physical structure.
That distinction matters because insurance coverage for the dwelling is generally based on the estimated cost to repair or rebuild the home, subject to the terms and limits of the policy, rather than simply its current selling price.
A house that could sell for $400,000, for example, does not necessarily have a $400,000 rebuilding cost. The numbers can be higher or lower depending on the property and local conditions.
Construction Costs Can Change Without You Noticing
You don’t have to renovate your home for its replacement cost to change. The cost of lumber, roofing materials, skilled labor, electrical work, plumbing and other construction services can move over time.
If your policy’s dwelling limit has remained unchanged for years, it is worth reviewing whether the amount still reflects current rebuilding conditions.
This doesn’t mean a homeowner should simply increase coverage by guessing a larger number. Insurance companies may use replacement-cost estimates, property details and other information to determine an appropriate amount. The important point is that the calculation shouldn’t be treated as permanent.
Your Belongings Are Another Story
The structure of your home isn’t the only thing that could be affected by a major loss. Furniture, electronics, clothing, appliances and other personal belongings can also represent a substantial amount of money.
Many people have no idea how much it would cost to replace everything they own. That’s why creating a basic home inventory can be useful. You don’t necessarily need a complicated document covering every inexpensive item. Photos, receipts for major purchases and a simple record of valuable belongings can make it much easier to understand what you own.
If a claim occurs, having records can also make the process of documenting your belongings more manageable.
Some of Your Most Valuable Items May Have Special Limits
Another detail that can surprise homeowners is that certain categories of personal property may have special limits under a policy. Jewelry, collectibles, cash, firearms, electronics and other high-value items may be subject to particular rules or sublimits depending on the policy.
This is one of those situations where simply saying “my belongings are insured” doesn’t tell the whole story.
Someone with a valuable jewelry collection, expensive camera equipment or rare collectibles may need to pay particular attention to the policy language and ask the insurer whether additional coverage is available.
Flood Damage Is a Separate Issue for Many Homeowners
Many homeowners assume that a standard homeowners policy covers every type of water-related damage. That assumption can create a serious problem.
Flood insurance is generally separate from standard homeowners insurance. Water entering a home because of a flood can therefore be treated differently from certain other types of water damage covered under a homeowners policy.
The definition of a covered loss can depend on the circumstances and the policy language, which is why homeowners in areas exposed to flooding should understand exactly what protection they have before a major storm arrives.
What About Temporary Living Expenses?
Imagine that your home becomes unlivable after a covered loss. Even if the physical repairs are eventually paid for, you may have immediate expenses for a hotel, temporary rental, meals or other additional living costs.
Some homeowners policies include loss-of-use or additional living expense coverage for qualifying situations, subject to policy terms and limits.
This is an important part of the policy to understand because the financial impact of a disaster isn’t always limited to the damaged property itself. Being unable to live in your home can create a second set of expenses that arrive at exactly the wrong time.
Home Improvements Can Change Your Insurance Needs
A new roof, finished basement, renovated kitchen, home office or other major improvement can change the value and characteristics of your property.
That’s why significant renovations are worth discussing with your insurer. If the home has changed substantially but the policy information hasn’t been updated, the coverage may not accurately reflect the property.
Even smaller changes can be worth reviewing when they involve expensive new equipment or valuable possessions.
The Cheapest Policy Isn’t Always the Same Policy
When homeowners compare insurance quotes, it can be tempting to focus almost entirely on the premium. But a lower price can come with different deductibles, limits, exclusions or coverage options.
A meaningful comparison requires looking at more than the monthly or annual cost. Two policies with similar premiums may provide different levels of protection, while two policies with different prices may also differ significantly in what they cover.
The question isn’t simply which policy costs less.
It’s what protection you’re receiving for that price.
The Five-Minute Policy Check That Could Be Worth Doing
You don’t need to become an insurance expert to understand the most important parts of your policy. Start by checking your dwelling coverage limit, deductible, personal-property coverage, additional living expense coverage and major exclusions.
Then think about what’s changed since you originally purchased the policy.
Did you renovate the house? Buy expensive electronics? Add jewelry? Start working from home? Acquire valuable collectibles? Experience major changes in your household?
Those changes may be a good reason to review your coverage.
The Question to Ask Before You Need the Insurance
Insurance is easiest to ignore when everything is going well. That’s also when it is easiest to review.
A policy is supposed to help you manage the financial consequences of unexpected events, but its protection depends on the coverage, limits, conditions and exclusions that were actually purchased.
So instead of asking only, “How much is my homeowners insurance?”, ask a more revealing question:
“If something happened to my home tomorrow, would my policy provide the protection I think I’m paying for?”
That question takes a little more effort to answer—but discovering the answer before a disaster is far better than discovering it afterward.
Table of Contents