Table of Contents
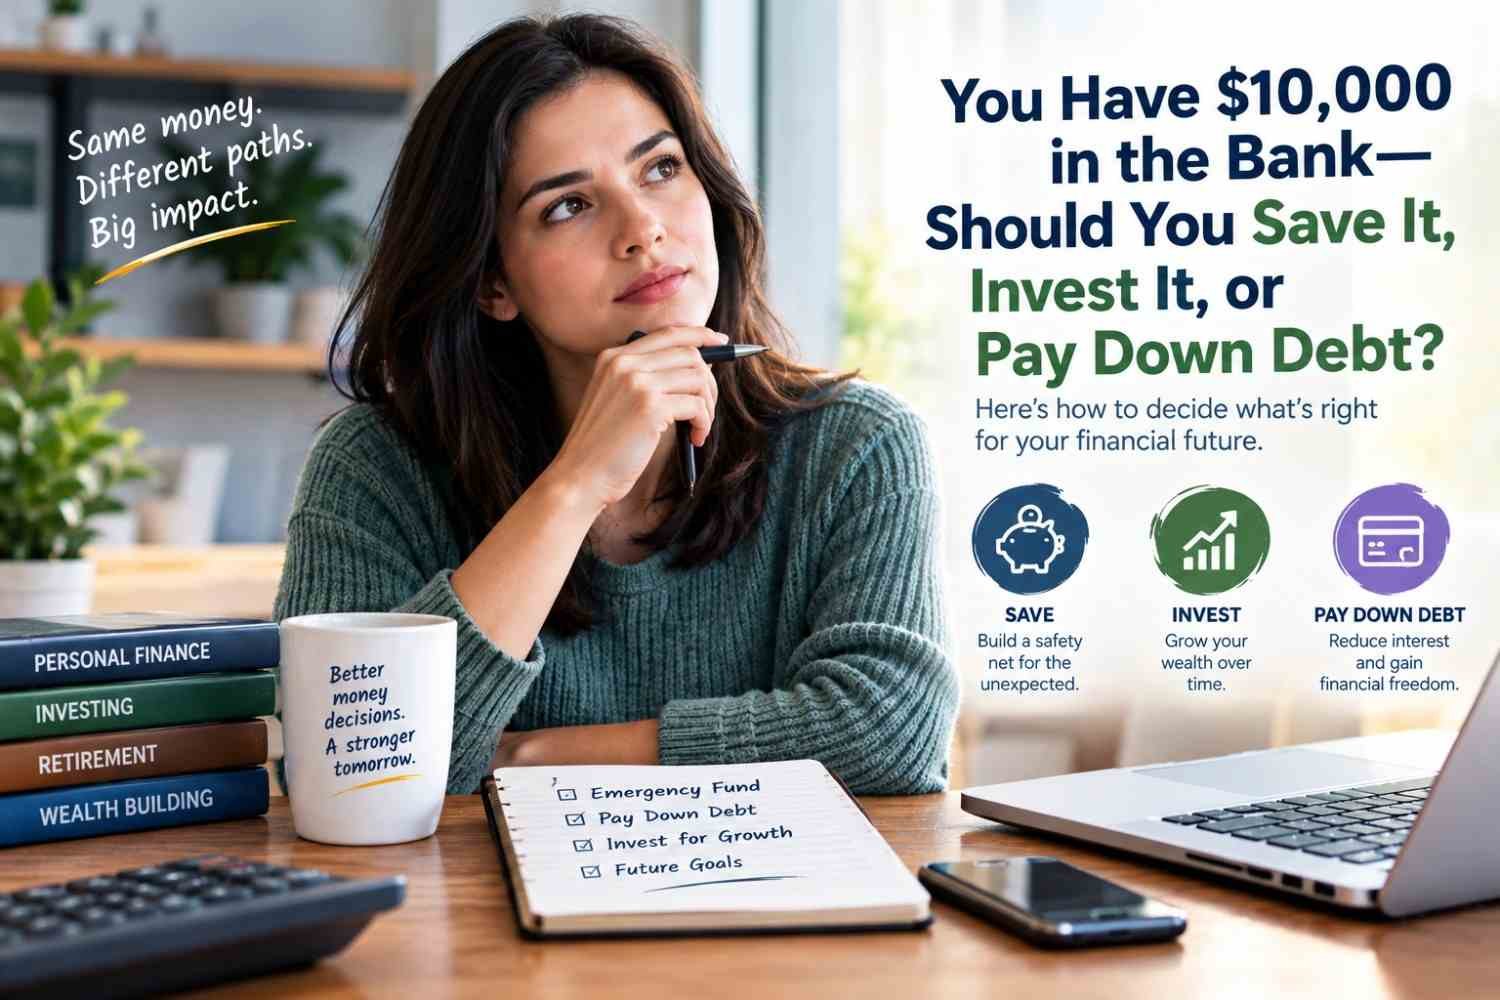
Having $10,000 sitting in your bank account can feel like a financial victory. But once you have that money, an even more important question appears: what should you actually do with it?
Leaving everything in cash can provide security, but your money may not grow much over time. Investing can create long-term wealth, but the value of investments can fall. Paying off debt can produce a guaranteed financial benefit, but putting every dollar toward debt could leave you without enough cash for an emergency.
There is no single answer that works for every household. The smartest decision depends on what the money is for, how soon you may need it, what kind of debt you have, and how much financial risk you can comfortably handle.
For many Americans, the best strategy is not choosing just one option. It is dividing the money according to its different jobs.
First Ask: What Is This $10,000 Supposed to Do?
Before moving money into a brokerage account, paying down a loan, or putting it into another financial product, determine what the money actually represents.
Money needed for rent, a home purchase, tuition, a vehicle, or another major expense within the next few years should generally be treated differently from money intended for retirement decades from now.
This distinction matters because investments designed for long-term growth can fluctuate significantly in the short term. A stock portfolio could be worth substantially less at exactly the moment you need the money.
Cash has a different advantage. It may not offer the same long-term growth potential as investments, but it gives you something investments cannot guarantee: immediate availability without having to sell assets after a market decline.
Your Emergency Fund Comes Before Your Investment Portfolio
One of the biggest mistakes people make after receiving a financial windfall is investing the entire amount immediately.
It can be tempting to think about compound growth and imagine what $10,000 could become over several decades. But an investment account cannot pay your unexpected medical bill simply because the stock market had a good year.
An emergency fund is designed for exactly those moments.
An unexpected job loss, major car repair, urgent home expense, or other financial shock can force you to borrow money at unfavorable terms when you do not have accessible cash. Having a dedicated reserve can reduce the chance that a temporary problem turns into expensive debt.
How much you need depends on your household, income stability, essential expenses, and circumstances. Someone with highly predictable income may approach an emergency reserve differently from someone whose income changes dramatically from month to month.
The important idea is simple: money that protects you from emergencies has a different job from money intended to build wealth.
High-Interest Debt Can Change the Entire Calculation
Now consider a different situation.
Suppose you have $10,000 in savings but also carry expensive credit card debt. In that case, investing the entire amount may not be the obvious first move.
Interest on revolving debt can work against you every month. Unlike an investment return, the cost of that debt is not something you can simply ignore because the market is expected to perform well over a long period.
Paying down expensive debt effectively removes future interest costs associated with that balance. That can provide a highly predictable financial benefit compared with an investment whose future return is uncertain.
This is why personal finance decisions often involve an unusual question: What return are you guaranteed by eliminating the debt?
If paying down a debt prevents a substantial amount of future interest from accumulating, that can be financially compelling.
But Do Not Drain Your Savings to Reach Zero Debt
There is another trap here.
Imagine using every dollar of your savings to eliminate debt, only to have an emergency two weeks later. You could then end up using a credit card or taking out another loan to cover the expense you just created.
That defeats part of the purpose.
A better approach for many households is to maintain an appropriate cash reserve while directing additional money toward high-cost debt. The exact split depends on your situation, but the principle is important: being debt-free is less useful if you have no financial cushion at all.
Financial flexibility has value.
What About Investing the Money?
Once your emergency savings are in place and expensive debt is under control, investing becomes much more attractive for money you do not expect to need soon.
The reason is time.
Long-term investing gives your money an opportunity to benefit from growth and compounding over many years. The longer the investment horizon, the more opportunity there is to absorb periods when markets decline and potentially recover afterward.
For a retirement-focused investor, that could mean using tax-advantaged accounts when appropriate. Depending on eligibility and circumstances, Americans may have access to accounts such as a 401(k), 403(b), traditional IRA, Roth IRA, or other retirement vehicles.
Each account has different rules, tax treatment, contribution limits, and eligibility requirements, so choosing the right account can matter almost as much as choosing the investment inside it.
The Account Is Not the Investment
This distinction causes confusion for a lot of new investors.
A retirement account is generally a type of account or tax structure. It does not automatically mean your money is invested.
For example, opening an IRA does not by itself create a diversified portfolio. Money can remain in cash inside an account unless you actually select investments.
Similarly, a brokerage account is simply the vehicle that allows you to buy and sell investments. The risk and potential return depend largely on what you hold inside it.
That means there are really two separate decisions:
Where should you hold the money?
And:
What should the money be invested in?
Keeping those questions separate can make financial decisions much easier to understand.
You Do Not Have to Invest All $10,000 at Once
Some people hesitate to invest because they are afraid of putting a large amount of money into the market immediately.
Others make the opposite mistake and assume they should move everything into investments as quickly as possible.
There is another option: investing gradually.
Instead of putting the entire amount into the market on a single day, an investor can spread purchases over multiple periods. This approach can make the emotional experience of investing easier for some people because it reduces the feeling that one particular market day determines the outcome.
However, investing gradually also means some money may remain uninvested for longer. Whether that trade-off makes sense depends on the investor’s goals, time horizon, and comfort with market volatility.
The larger lesson is that a strategy you can consistently follow may be more useful than one that looks perfect on paper but causes you to panic during a market downturn.
Where Should Short-Term Money Go?
Not every dollar needs to be invested in stocks.
Money you may need relatively soon can be held in vehicles designed primarily for preservation and accessibility rather than aggressive growth.
Depending on the purpose and time horizon, options people may consider include savings accounts, high-yield savings accounts, money market products, certificates of deposit, Treasury securities, or other cash-management choices.
Each has different characteristics involving liquidity, interest, maturity, taxes, and risk.
The key is to match the financial product to the job the money needs to perform.
Money needed for next year’s expenses should not necessarily be treated the same way as money intended for retirement in 25 years.
Taxes Can Quietly Change Your Results
An investment that looks attractive before taxes may produce a different result after taxes.
The tax treatment of investment income, capital gains, dividends, interest, and retirement withdrawals can vary depending on the account and the investor’s circumstances. State taxes can also matter.
This is one reason tax-advantaged accounts can be especially valuable for long-term investors who qualify to use them.
However, tax considerations should not become an excuse to buy a product simply because someone says it is “tax efficient.” The underlying investment, fees, liquidity, and overall suitability still matter.
A tax benefit is useful only when the financial product itself makes sense for your situation.
Fees Can Eat Into Long-Term Wealth
A difference that looks tiny on paper can become meaningful over decades.
Investment products can have management fees, expense ratios, trading costs, advisory charges, account fees, or other expenses. The exact structure varies widely.
Suppose two investments have similar performance before fees. The lower-cost option may leave more money in the investor’s account over the long run, particularly when the difference compounds over many years.
That does not mean the cheapest financial product is automatically the best. Some investors may reasonably pay for services or features they value. But every fee should have a clear purpose.
Ask what you are paying, how often you are paying it, and what you receive in exchange.
What If You Are Saving for a House?
The answer changes again when your $10,000 has a specific near- or medium-term goal.
Someone saving for a down payment may prioritize stability and liquidity over maximum long-term investment growth. A major market decline shortly before a planned home purchase could create a serious problem.
The same principle applies to other major purchases.
A house, wedding, tuition expense, business launch, or vehicle purchase has a timeline. The shorter the timeline, the more important it can become to protect the money from large short-term fluctuations.
This is why financial planning is not simply about asking, “What earns the most?”
A better question is:
What gives this particular dollar the best chance of doing its job when I need it?
A Simple Way to Divide the Money
Imagine you receive $10,000 and have no immediate major purchase planned.
Instead of asking whether you should “save or invest,” you could think about the money in layers.
The first layer is your emergency reserve.
The second layer is expensive debt that may be costing you significant interest.
The third layer is money for shorter-term goals.
The fourth layer is genuinely long-term money that you can leave invested through market ups and downs.
That framework can help prevent an emotional decision based entirely on what the stock market, interest rates, or financial headlines happen to be doing at the moment.
The Biggest Financial Advantage May Be Flexibility
A strong financial position is not necessarily the one with the largest investment account.
It can also be the one where an unexpected $2,000 expense does not force you to sell investments, borrow money, or miss a bill.
That is why liquidity is valuable.
Cash reserves can give you time. Investments can provide long-term growth potential. Debt reduction can lower future interest costs. Retirement accounts can provide tax advantages under applicable rules.
Each tool has a different purpose.
Trying to make every dollar perform the same job can create unnecessary risk.
What Wealthy Investors Often Understand About Cash
There is a common misconception that sophisticated investors never keep significant amounts of cash because cash is “dead money.”
In reality, cash can be strategic.
Cash can provide liquidity during uncertain periods, cover planned expenses, allow investors to avoid selling long-term assets at an inconvenient time, and create flexibility when opportunities appear.
The important distinction is between unproductive cash that has no clear purpose and cash that is intentionally reserved for a specific need.
A healthy financial plan can contain both cash and investments without treating either one as automatically superior.
The Real Question Is Not “Save or Invest?”
The biggest mistake may be assuming your $10,000 has to receive one single label.
It does not.
Part of it might belong in an emergency fund. Another part might eliminate expensive debt. Another portion could be reserved for a near-term goal. And money that you genuinely will not need for many years may be better suited to a diversified long-term investment strategy.
The right combination depends on your income, expenses, debt, goals, time horizon, tax situation, and tolerance for investment losses.
That is what makes personal finance personal.
Before You Move the Money, Run These Five Checks
Before transferring $10,000 into any financial product, take a moment to look at the bigger picture.
Do you have enough accessible cash for a meaningful emergency?
Do you carry high-interest debt?
Will you need this money within the next few years?
Are you taking full advantage of employer retirement benefits that may be available to you?
And do you understand the fees, taxes, risks, and withdrawal rules associated with the account or investment you are considering?
Those questions can prevent a surprisingly expensive mistake.
Your $10,000 Is More Than a Balance on a Screen
Money becomes powerful when you give it a purpose.
A dollar sitting in savings is providing liquidity. A dollar used to pay down costly debt is reducing future interest expense. A dollar invested for retirement is attempting to grow over the long term. A dollar reserved for a home purchase is protecting a future goal.
None of those choices is automatically right for everyone.
The smartest move is usually the one that fits the timeline of the money, protects your financial foundation, and supports the goals you are actually trying to achieve.
So the next time you look at $10,000 in your bank account, do not ask only, “How much could this earn?”
Ask the more important question:
“What job do I need this money to perform?”
That answer may tell you more about what to do with it than any financial headline ever could.